Yes. Cameras, lights, microphones and editing software used for your content are allowable. A phone or broadband you also use personally is claimed for the business share. If you film or edit at home, you can claim a flat rate or a share of your household costs, including rent. This guide shows how each one works.
Key takeaways
- Equipment and software used only for your content are claimable in full.
- Phone and broadband with some personal use are claimed for the business share.
- For working from home, you can use HMRC's flat rates of £10, £18 or £26 a month, or claim a share of actual costs.
- The flat rate doesn't include phone or internet, which you claim separately.
- A reasonable split based on a real record is what HMRC expects.
Can you claim cameras, lights and other equipment?
Yes. Equipment you buy to create content is a business cost: cameras, lenses, tripods, ring lights, microphones, capture cards, a computer for editing. GOV.UK says equipment can be claimed as allowable expenses if you use cash basis accounting, which is the default for most sole traders, or through capital allowances if you use traditional accounting.
If you also use an item personally, such as a laptop you edit on and watch films on, claim the business share only.
Can you claim editing software and subscriptions?
Yes. Editing software, stock music and footage, scheduling tools, cloud storage and thumbnail tools are allowable where you use them for your content. Subscriptions you'd have anyway for personal use are not.
Can you claim your phone?
Yes, for the business share. GOV.UK lists "phone, mobile, fax and internet bills" as allowable, and adds that you "cannot claim for any non-business use". If one phone does everything, work out a reasonable business proportion from how you actually use it.
Worked example
Illustration only. Dan's phone contract is £40 a month. Looking at a typical month's usage, about 70% of it is filming, editing, posting and dealing with brands. Dan claims £40 × 12 × 70% = £336 for the year. If Dan bought a second phone used only for the channel, that phone and its contract would be claimable in full.
Can you claim for working from home?
Yes, if you film, edit or run your creator business from home. There are two methods.
Method 1: HMRC's flat rate
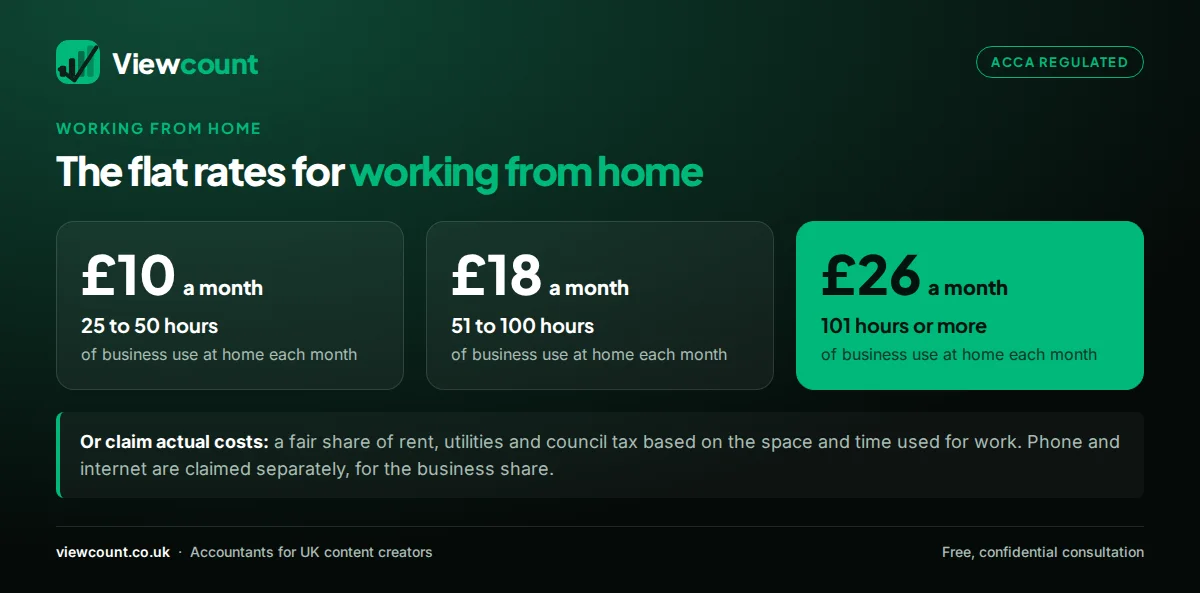
| Hours of business use at home each month | Flat rate |
|---|---|
| 25 to 50 | £10 a month |
| 51 to 100 | £18 a month |
| 101 or more | £26 a month |
The flat rate is simple and needs no bills. A creator working 120 hours a month from home claims £26 × 12 = £312 a year. It does not include phone or internet, which you claim separately for the business share.
Method 2: a share of actual costs
Add up your household running costs and claim a fair proportion based on the space you use and how long you use it for work. GOV.UK says you can claim "only the part that's used for business". Costs that can go in include rent, gas and electricity, water and council tax.
This usually gives a larger claim than the flat rate if you rent and have a dedicated filming or editing room, but you need the bills and a sensible method.
Watch out
A room used only for business part of the time is safer than claiming it as 100% business. If you own your home, exclusive business use of a room can affect Capital Gains Tax relief when you sell. Take advice before you claim that way.
Can you claim part of your rent?
Yes, under the actual-cost method. If you rent and use part of your home for your creator business, a fair share of the rent is allowable. If you have a mortgage, the same logic applies to the interest, but not to the capital repayments.
Can you claim broadband?
Yes, for the business share. Uploading and streaming often make up a large part of a creator's usage, but a household connection is rarely 100% business. Pick a proportion you can explain.
Want your equipment and home office claims worked out properly? We'll do it for you. See our bookkeeping service.
Get in touchHow do you work out a business share?
HMRC accepts a proportion based on a detailed review of a representative period. Track your use for a typical month, work out the business share, and keep using it until your circumstances change. Keep the workings.
From April 2026, creators with qualifying income over £50,000 keep these records digitally under Making Tax Digital. For more claimable costs, see 10 tax-deductible expenses for UK creators.
FAQs
Sources
- GOV.UK: expenses if you're self-employed, office and property
- GOV.UK: simplified expenses, working from home
- HMRC Business Income Manual BIM37007: wholly and exclusively, apportionment
This article is general information for UK content creators based on HMRC rules and rates at the date reviewed. It is not personal tax advice; your circumstances may differ. Talk to us before acting on it.
Claim everything you're entitled to
We'll work out your equipment, phone and home office claims properly.
Book a free consultation